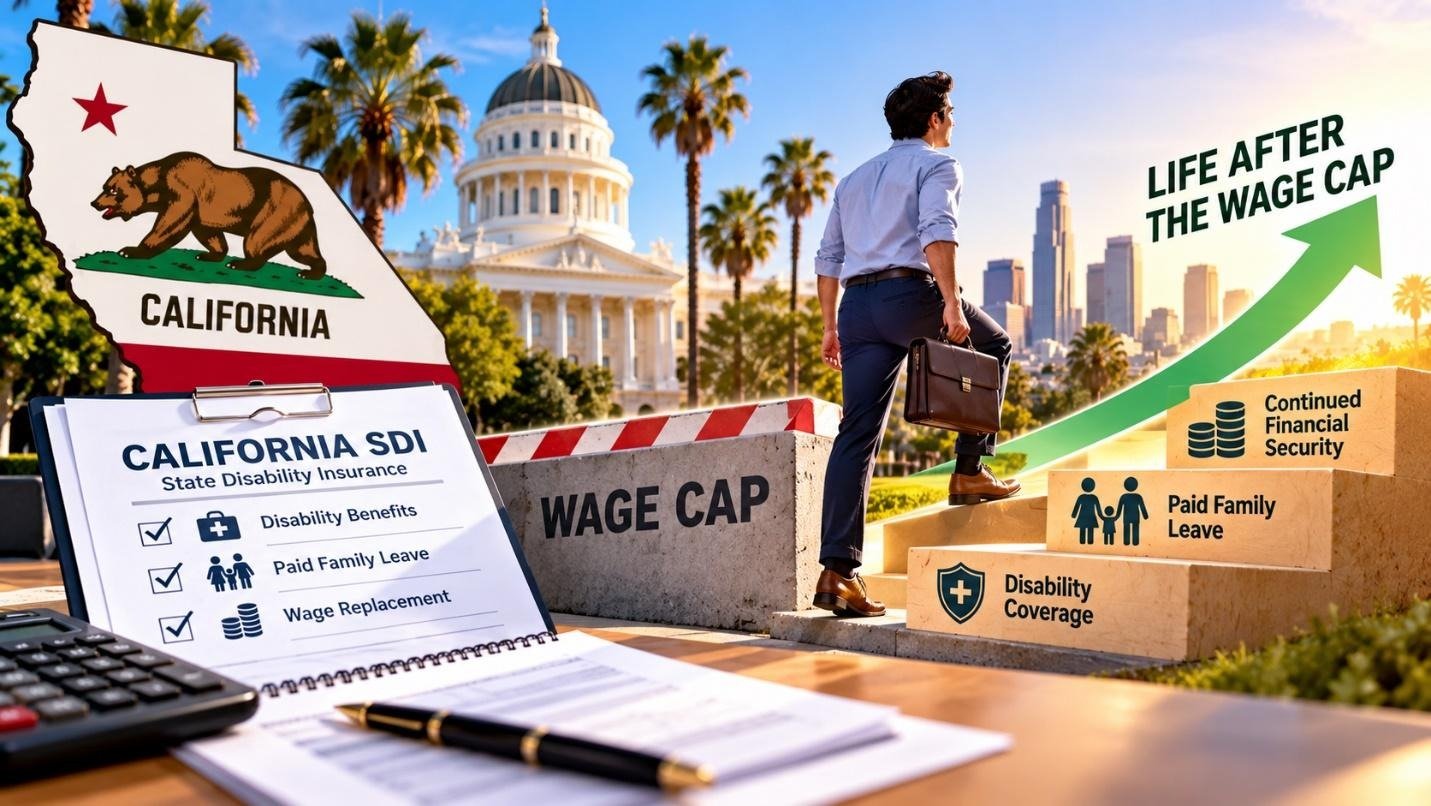
Senate Bill 951 amended California’s State Disability Insurance (SDI) system to eliminate the cap on wages covered by the program and the maximum contribution for employees, effective Jan. 1, 2024. For 2026, the SDI withholding rate is 1.3% of all wages covered by SDI, and there is no cap on the number of wages subject to withholding.
That shift can have a huge impact on the amount of money taken out of the high earner’s paycheck, particularly for executives and tech workers who receive large bonuses or equity shares. Look for an expert (like a California tax attorney) who can help you with tax matters.
What’s New with California SDI?
Prior to 2024, California had capped annual wages from which to calculate SDI. In most cases, wages were no longer subject to SDI withholding once an employee reached the wage ceiling.
That ceiling disappeared under SB 951.
For 2026:
- SDI rate: 1.3%
- No ceiling on SDI wage base.
- No more than 25% of employees will contribute.
- All covered wages are subject to SDI.
The EDD reports that SDI is not added to the employee’s wages, but instead is deducted from the employee’s wages, and is not a separate employer payroll tax.
What Does the 1.3% Rate Mean for High Earners?
The tax does not have a cap on wages, so it remains even as earnings grow.
If the rate is 1.3%, for example:
- $100,000 in wages = $1,300 SDI
- $250,000 = $3,250
- $500,000 = $6,500
- $1 million = $13,000
They are examples of situations where all compensation is subject to SDI and show the withholding effect. The withholding effect may differ depending on individual payroll situations.
The EDD’s example for 2026 is $180,000 in annual wages resulting in $2,340 in SDI withholding at 1.3%.
Why are Bonuses and Executive Compensation Important?
There are a number of ways that high earners can receive compensation, such as salary, annual bonuses, commissions, and other taxable wages.
A large bonus will not automatically avoid SDI withholding because the employee has already earned a lot of wages earlier in the year if there is no SDI wage ceiling.
This could make the extra pay at the end of the year stand out.
For instance, if an executive is paid $300,000 in salary and another $200,000 in taxable bonus, they may have $500,000 of covered wages for the year. At the 2026 rate, the illustrative SDI withholding would be $6,500.
Employers thus need to make sure their payroll software integrates SDI into relevant compensation during the year. Consultation with an expert (like an EDD audit attorney) will surely help you in the long run.
Effect on innovative technology and high-growth businesses
The compensation packages for technology workers in California often include equity-related compensation, commissions, bonuses, and salary.
The elimination of the SDI ceiling may influence an employee’s overall compensation package.
If the employer competes for highly compensated personnel, then it may be a component of a larger compensation conversation:
- Base salary
- Annual and performance bonuses
- Equity compensation
- Benefits
- Paid leave
- Retirement benefits
- Tax-related payroll effects
The withholding of the SDI itself will be paid by the employee but may still be a factor when a worker is making a comparison in terms of net income.
Are there higher benefits with higher SDI Withholding?
Not always in correlation to the extra taxes paid.
The maximum rate for Disability Insurance in California in 2026 is $1,765, even though there is no cap on wages that are taxable. A worker’s benefits typically will not grow with income; the EDD will generally pay up to the amount of the weekly maximum to qualified claimants with adequate earnings, but won’t pay more than that even if their earnings keep rising.
This is a significant difference, as high earners can pay SDI on unlimited covered wages, whereas benefit payments are capped at the statutory maximums.
Employers and High Earners Should Consider the Following Tips:
To successfully deal with the change:
- Review payroll settings. Assure that systems are no longer subject to the old SDI ceiling on wages.
- Plan for incentives to the model. There is large additional SDI withholding that can result from large incentive payments.
- Check out Executive compensation statements. Ensure that employees are aware of the difference between gross compensation and net pay.
- Coordinate equity payroll. Review applicable treatment of wages for taxable equity compensation.
- Plan on annual withholding. Don’t assume that if you make too much, SDI doesn’t apply.
- Review EDD guidance on an annual basis. The rate of the contributions to the SDI may vary from one year to the next.
The move to eliminate the SDI wage ceiling in California has overhauled the way high earners’ payroll is calculated. For 2026, the 1.3% SDI rate is not capped at an annual limit, and bonuses and high levels of income are subject to withholding throughout the year.
It is important for executives, technology professionals, and employers who are developing competitive compensation packages to know about this uncapped withholding for proper payroll forecasting and realistic take-home-pay expectations.
